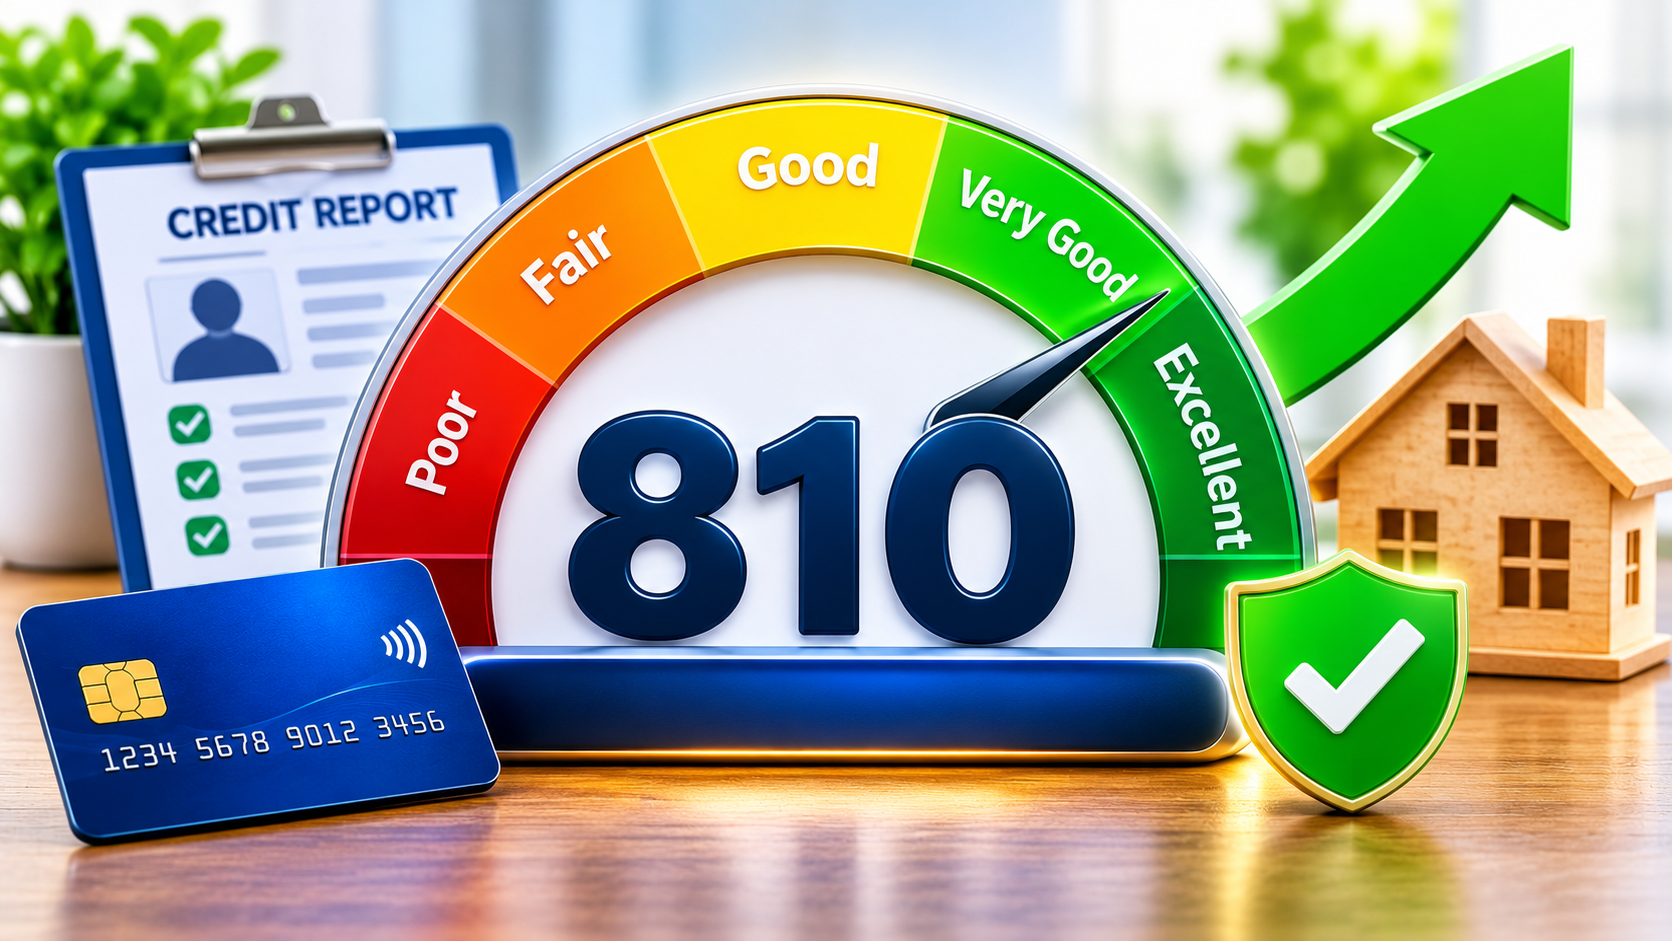
A credit score is one of the most important numbers lenders consider when evaluating your financial reliability. Whether you want to apply for a premium credit card, purchase a car, qualify for a mortgage, or obtain a personal loan, your credit score can influence your approval chances and borrowing costs. If your current score is 810, you are already in a very strong financial position from a credit-scoring perspective. An 810 credit score is considered exceptional under the standard FICO scoring model and excellent under VantageScore. It places you in the highest FICO credit category and indicates that you have demonstrated responsible credit management over time. Consumers with scores at this level generally have a strong history of handling credit obligations. An 810 score may help you qualify for competitive interest rates, premium credit cards, and favorable loan terms. However, having an exceptional score does not guarantee approval or the lowest possible interest rate. Lenders also evaluate income, existing debt, employment, and other financial information. Is an 810 Credit Score Good? Yes, an 810 credit score is excellent. Under the standard FICO model, scores of 800 and above fall into the exceptional category. This is the highest general-purpose FICO credit rating. Lenders generally view borrowers with exceptional scores as lower-risk applicants because their credit histories often demonstrate consistent payments and responsible borrowing habits. With an 810 score, you may have access to a wide range of financial products, including premium credit cards, competitive auto loans, conventional mortgages, and personal loans. Understanding FICO credit score ranges The following table explains the commonly used FICO credit score categories: FICO Credit Score Rating 300–579 Poor 580–669 Fair 670–739 Good 740–799 Very Good 800–850 Exceptional An 810 score is comfortably within the exceptional category. You are 40 points away from the maximum possible FICO score of 850. What does 810 mean under VantageScore? VantageScore 3.0 and 4.0 also use a 300–850 scoring scale, but their rating categories are different. VantageScore Range Rating 300–600 Subprime 601–660 Near Prime 661–780 Prime 781–850 Superprime Under VantageScore, an 810 score falls into the superprime category. Therefore, whether you are checking FICO or VantageScore, 810 represents an excellent credit position. How Does an 810 Credit Score Compare With the National Average? An 810 FICO score is significantly higher than the average credit score in the United States. According to FICO’s Fall 2026 Credit Insights report, the average U.S. FICO score was 714. This means an 810 score is 96 points above the national average. It also places you in a credit category that demonstrates a strong record of financial responsibility. Why the national average matters Comparing your score with the national average helps you understand your general position among U.S. consumers. However, lenders do not approve applications simply because your score is above the average. For example, someone with an 810 score may receive a favorable loan offer, but a lender can still consider their income, debt-to-income ratio, loan amount, and employment situation. Your score is an important advantage, but maintaining a healthy overall financial profile remains essential. Can You Get a Credit Card With an 810 Credit Score? Yes, an 810 credit score can make you a strong candidate for many credit cards. You may qualify for premium rewards cards, travel credit cards, cashback products, and cards with attractive introductory offers. Credit card issuers generally consider applicants with exceptional credit to be lower-risk customers. This can increase your chances of qualifying for products with valuable benefits. Credit card options you may consider With an 810 score, you can explore several types of credit cards: How to choose the right credit card A high credit score does not mean you should apply for every premium card available. Compare annual fees, rewards structures, interest rates, and eligibility requirements. If a card charges a substantial annual fee, make sure its benefits provide enough value to justify the cost. You should also avoid unnecessary applications because hard inquiries can temporarily affect your credit score. Can You Buy a House With an 810 Credit Score? Yes, an 810 credit score can put you in a strong position when applying for a mortgage. It is well above the minimum credit requirements for many conventional and government-backed mortgage programs. A high score may improve your chances of qualifying for competitive mortgage pricing. However, the actual interest rate depends on several factors, including the loan type, down payment, property details, debt-to-income ratio, and lender requirements. Conventional mortgage loans Conventional mortgages are offered by private lenders and generally follow guidelines established by Fannie Mae and Freddie Mac. An 810 score is significantly above common minimum credit requirements for many conventional loan products. This may help you qualify for favorable terms, depending on the rest of your financial profile. FHA mortgage loans FHA loans are backed by the Federal Housing Administration and are designed to make homeownership more accessible. Under standard FHA guidelines, borrowers with qualifying scores of 580 or higher may be eligible for a down payment as low as 3.5%. Borrowers with scores between 500 and 579 generally need a down payment of at least 10%. With an 810 score, you are well above these commonly cited thresholds. However, FHA loans also involve mortgage insurance, lender requirements, and other eligibility conditions. How to make the most of your credit score If you are planning to purchase a home, compare mortgage offers from several lenders. Even with exceptional credit, different lenders may offer different interest rates, fees, and closing costs. Review the annual percentage rate, total loan expenses, and repayment terms instead of focusing only on the advertised interest rate. Is an 810 Credit Score Good for a Car Loan? Yes, an 810 credit score is excellent for an auto loan application. It may help you qualify for some of the most competitive financing offers available to eligible borrowers. Auto lenders generally evaluate credit scores to estimate repayment risk. Applicants with exceptional credit may receive more attractive interest rates than borrowers with fair or poor credit.