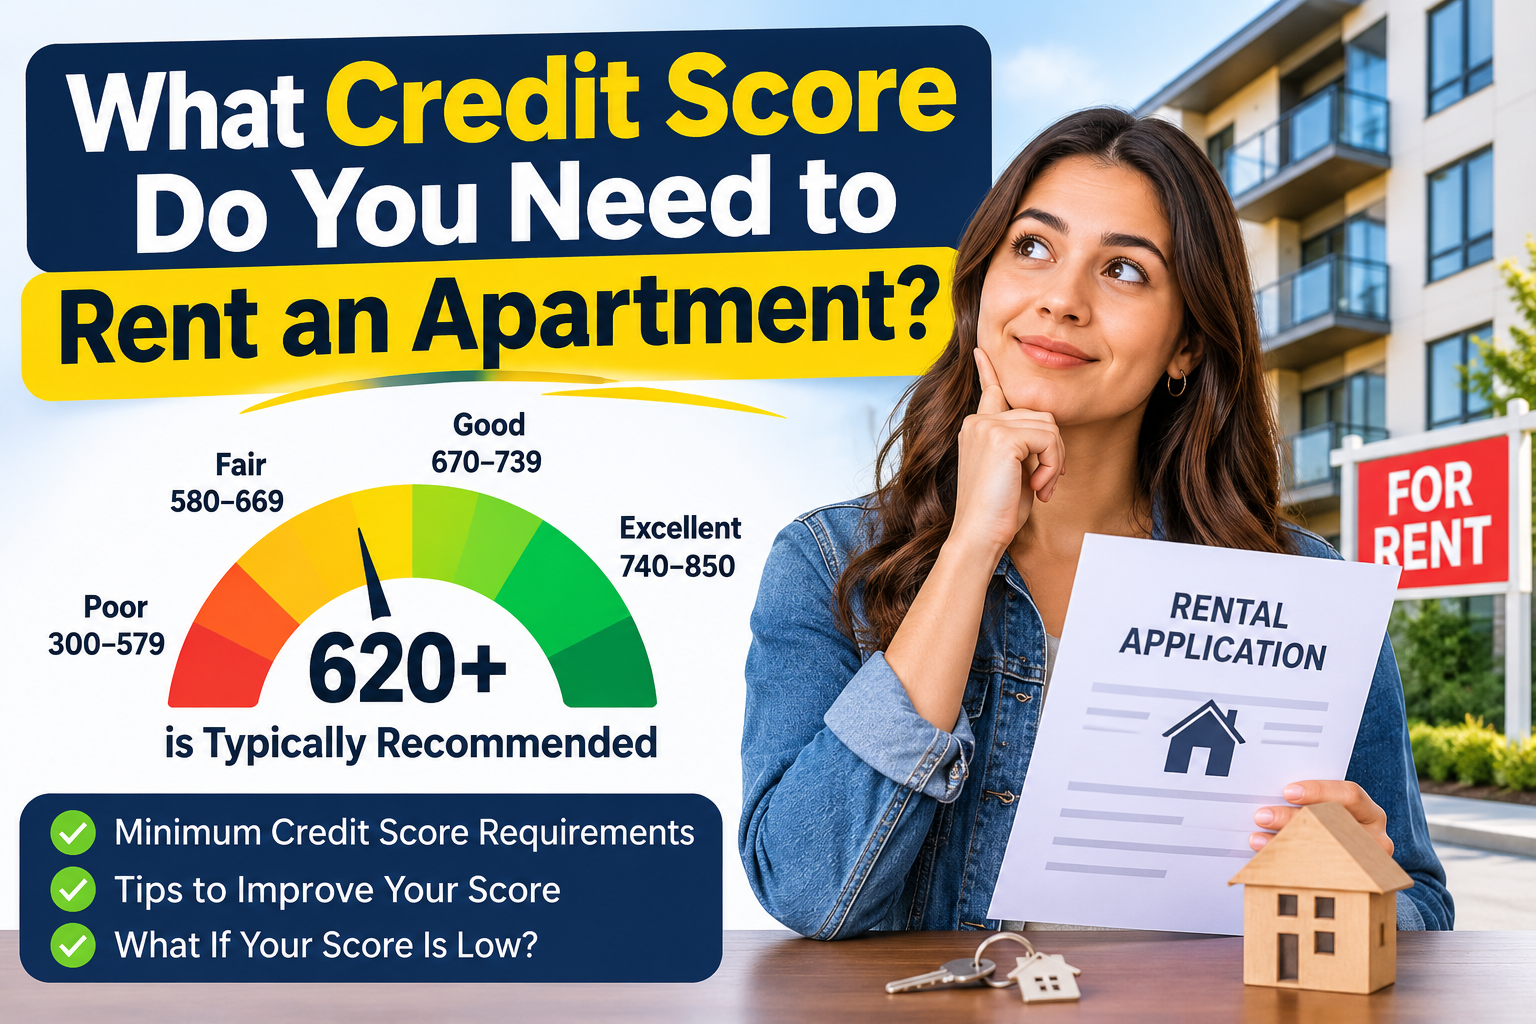
Finding the right apartment involves more than choosing a convenient location, comparing rent prices, and checking available amenities. Before approving a rental application, many landlords and property management companies review an applicant’s financial background to understand whether they can consistently pay rent on time. One important part of this process is the credit score. There is no universal credit score requirement for renting an apartment in the United States. However, many landlords consider a score of 600 to 650 or higher acceptable, while a score above 670 may make an applicant more attractive. The exact requirement depends on the property, location, rental market, and individual landlord’s screening policies. Understanding how credit checks work can help you prepare a stronger application, avoid unnecessary rejections, and find a rental property that fits your financial situation. What Credit Score Do You Need to Rent an Apartment? Most landlords do not follow one nationwide credit score requirement. Each property owner or management company can establish its own screening standards. Some apartments may accept applicants with scores around 600, while more competitive properties may prefer scores above 680 or 700. A score of 600 to 650 can provide a reasonable starting point when applying for many rental properties. However, having a higher score can improve your chances, particularly when several applicants are competing for the same apartment. Here is a general guide to how landlords might view different credit score ranges: Credit Score General Rental Application Outlook 800–850 Excellent credit profile 740–799 Strong applicant 670–739 Generally favorable 600–669 May require additional review 580–599 Approval may be more difficult 300–579 May need additional financial support These categories are general guidelines based on common FICO score ranges, not official rental approval standards. A landlord may approve someone with a lower score if the applicant has reliable income and a positive rental history. Why Do Landlords Check Your Credit Score? Landlords want to reduce the financial risks associated with renting a property. When someone signs a lease, the property owner expects regular monthly payments throughout the rental agreement. A credit check provides information about how an applicant has handled financial responsibilities in the past. Payment History: Payment history is one of the most important parts of a credit profile. Landlords may review whether you have consistently paid credit cards, personal loans, auto loans, and other financial obligations on time. Frequent late payments can create concerns about your ability to meet monthly rent payments. Outstanding Debt: Your current debt obligations can influence a landlord’s decision. If you already have significant credit card balances, personal loans, or other monthly payments, the landlord may question whether you have enough income left to afford rent. Credit Utilization: Credit utilization measures how much of your available revolving credit you are using. For example, if your credit card limit is $5,000 and your balance is $4,000, your utilization is 80%. High utilization can negatively affect your credit score and may indicate financial pressure. Collections and Defaults: Unpaid accounts, debt collections, and loan defaults can raise concerns during tenant screening. Some landlords pay particular attention to recent negative information because it may indicate unresolved financial problems. Length of Credit History: A longer credit history can give landlords more information about your financial habits. Applicants with limited credit histories may need to provide additional documents to demonstrate financial reliability. What Other Factors Do Landlords Consider Besides Credit Scores? Your credit score is important, but it is rarely the only factor in a rental decision. Landlords generally evaluate your overall financial situation and rental background before approving an application. Monthly Income: Property owners want to know whether your income is sufficient to cover rent and other living expenses. A common screening guideline is monthly gross income of approximately three times the rent, although requirements vary. For example, an apartment costing $1,500 per month may require an applicant to demonstrate around $4,500 in gross monthly income. Employment Stability: A steady employment history can help demonstrate that you have a reliable source of income. Landlords may request recent pay stubs, employment verification, an offer letter, or bank statements to confirm your financial situation. Previous Rental History: Your relationship with previous landlords can influence your application. A history of paying rent on time, following lease conditions, and leaving properties in good condition can strengthen your profile. Eviction Records: Previous eviction proceedings or judgments may create challenges during tenant screening. Landlords may review available rental history and public records to understand whether an applicant has experienced serious rental problems. Savings and Financial Reserves: Having money saved in a bank account can provide additional reassurance. Savings may show that you have resources available to manage rent payments during unexpected financial difficulties. Background Screening: Some property managers also review identity information, criminal background records, and rental-specific screening reports. The exact information reviewed depends on the property owner’s policies and applicable laws. Can You Rent an Apartment With a Low Credit Score? Yes, renting an apartment with a low credit score is possible. Although some property management companies have strict credit requirements, other landlords consider an applicant’s complete financial profile. For example, someone with a 580 credit score might still qualify for an apartment if they have a stable job, sufficient income, positive rental references, and no recent rental payment problems. The key is to demonstrate that your current financial situation is stronger than your credit score might suggest. Find Independent Landlords: Individual property owners may have more flexibility than large apartment management companies. They may consider personal circumstances, employment stability, savings, and rental references instead of relying entirely on an automated credit screening system. Provide Proof of Income: Prepare recent pay stubs, employment letters, tax documents, or bank statements. These records can help demonstrate that you have enough money to manage monthly housing expenses. Offer a Qualified Co-Signer: A co-signer or guarantor with stronger credit and sufficient income may improve your application. However, this person generally agrees to take financial responsibility if you fail to meet the lease obligations. Show Previous Rental