Buying a car is a major financial decision, and your credit score can play an important role in determining how much you pay for it. Whether you are planning to purchase a new vehicle or a used car, lenders typically review your credit history before approving an auto loan. Your score can influence your loan approval chances, interest rate, monthly payment, and overall borrowing cost.
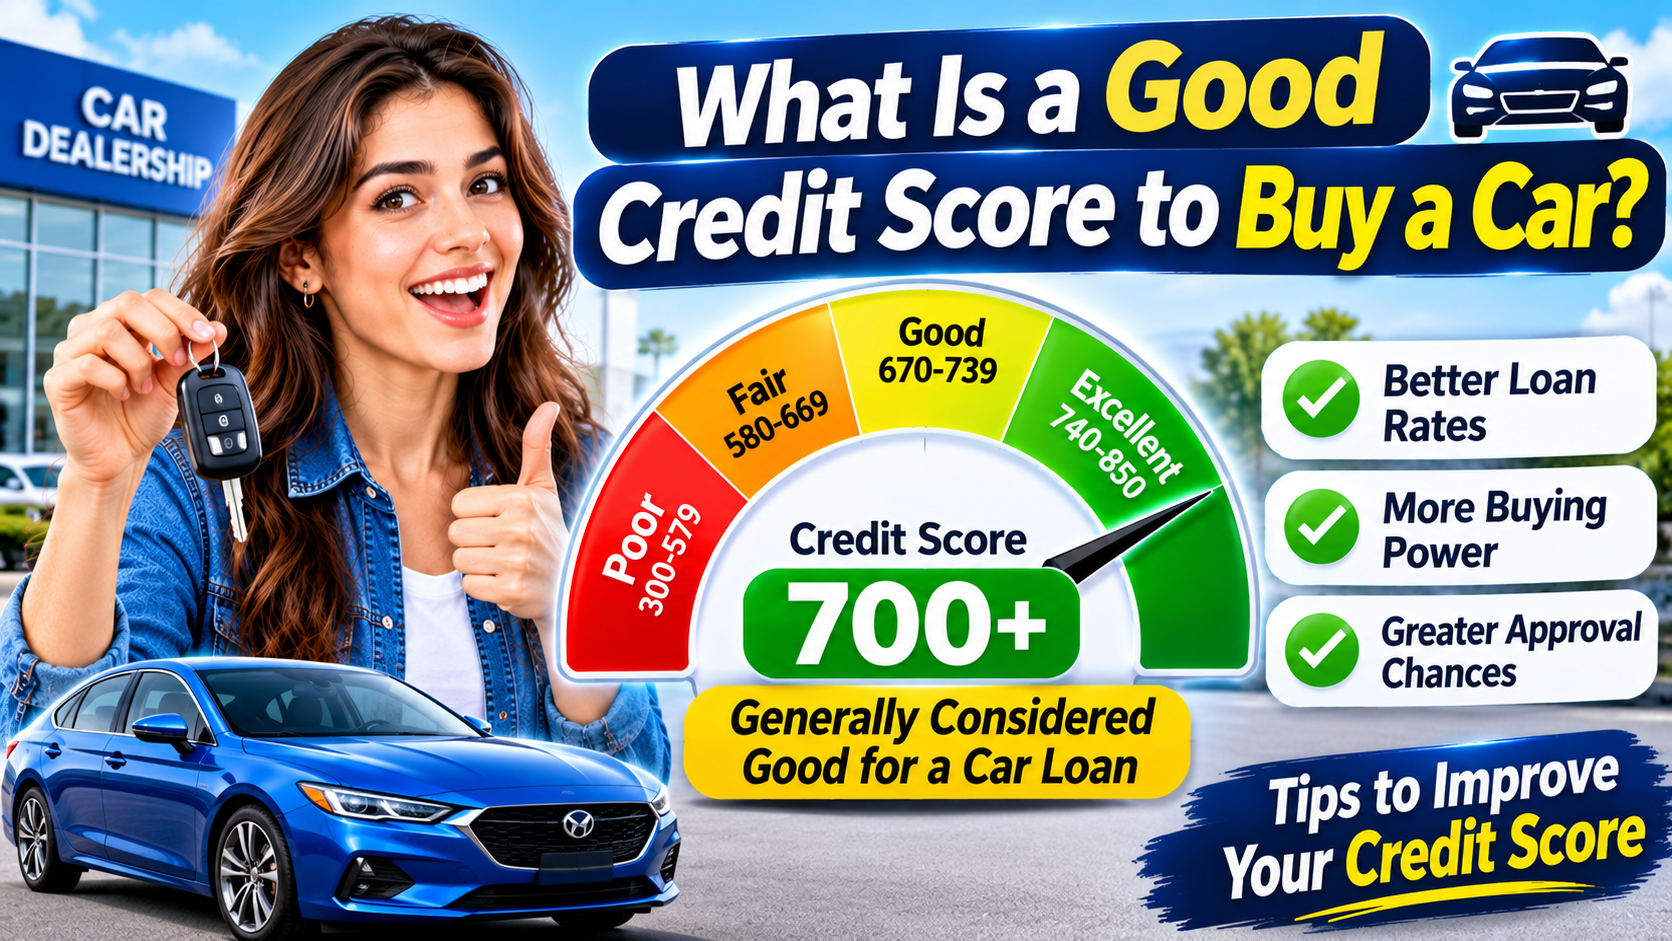
So, what is a good credit score to buy a car? In the United States, a score of 670 or higher is generally considered a good starting point for getting competitive auto loan offers. However, you may still qualify with a lower score, depending on your income, debt, down payment, loan term, and the lender’s requirements.
Understanding how credit scores affect car financing can help you prepare before visiting a dealership or submitting a loan application. This guide explains the credit score ranges, lender expectations, financing options, and practical ways to improve your chances of getting an affordable car loan.
What Credit Score Is Considered Good for Buying a Car?
A credit score of 670 or above is generally considered good under the FICO scoring system. Borrowers with higher scores often have access to better interest rates and more favorable loan terms.
However, there is no universal minimum credit score required to finance a car. Different lenders use different approval criteria, and some specialize in working with borrowers who have limited or poor credit histories.
Here is a general overview of FICO credit score ranges:
| FICO Score Range | Credit Category | Potential Auto Loan Experience |
| 300–579 | Poor | Limited options and higher interest rates |
| 580–669 | Fair | Financing may be available at higher rates |
| 670–739 | Good | More financing options and potentially competitive rates |
| 740–799 | Very Good | Strong chances of favorable loan terms |
| 800–850 | Exceptional | Often eligible for the most competitive offers |
These categories are general guidelines, not guaranteed lending decisions. An auto lender may also consider your income, employment stability, existing debts, and payment history.
What Credit Score Do You Need to Buy a New Car?
New car financing often comes with competitive promotional offers, but the lowest advertised interest rates are usually reserved for applicants with strong credit.
A score of 700 or higher can put you in a stronger position when applying for a new car loan. Borrowers with scores above 740 may have a better chance of qualifying for attractive financing offers, although approval still depends on the lender and the applicant’s complete financial profile.
Why credit matters for new car loans:
- Interest rates: Higher scores can help you qualify for lower borrowing costs.
- Loan approval: A strong credit history may improve your chances of approval.
- Promotional financing: Some manufacturer offers require excellent credit.
- Monthly payments: A lower interest rate can reduce the amount you pay each month.
For example, two people purchasing the same vehicle may receive different interest rates because their credit profiles are different. Even a small difference in the rate can add up over a loan lasting several years.
What Credit Score Do You Need to Buy a Used Car?
Used car financing can have different requirements from new car financing. Some lenders consider used vehicles riskier because they are older, may have higher mileage, and can depreciate differently from new vehicles.
A credit score of 670 or higher can help you access more competitive used car loan options. However, borrowers with scores in the fair or poor ranges may also find financing through certain banks, credit unions, and specialized auto lenders.
Before applying, consider these factors:
- The vehicle’s age and mileage
- The total purchase price
- Your down payment
- Your monthly income
- Your current debt obligations
- The lender’s vehicle financing policies
If your credit score is below 670, comparing several lenders may help you find an offer that fits your budget.
How Does Your Credit Score Affect Car Loan Interest Rates?
Your credit score can directly influence the interest rate offered by an auto lender. In general, borrowers with stronger credit profiles are considered less risky and may qualify for lower rates.
Borrowers with lower scores may face higher interest rates because lenders see a greater possibility of missed payments.
Consider a simplified example of a $25,000 auto loan with a 60-month repayment period:
| Annual Interest Rate | Approximate Monthly Payment |
| 4% | $460 |
| 6% | $483 |
| 9% | $519 |
| 12% | $556 |
| 15% | $595 |
These figures are illustrative estimates. They assume a $25,000 loan, fixed interest, and equal monthly payments. Actual offers depend on the lender, vehicle, credit profile, and loan terms.
The difference between a low and high interest rate can significantly affect the total cost of a vehicle. That is why checking your credit before applying for financing is worthwhile.
Can You Buy a Car With a 600 Credit Score?
Yes, it is possible to buy a car with a credit score of 600. A score in this range falls within the fair category under the commonly used FICO ranges, and some lenders offer auto financing to borrowers with fair credit.
However, you may not receive the same interest rates as someone with a score above 700.
To improve your chances of approval with a 600 credit score, consider the following steps:
1. Make a larger down payment
A larger down payment reduces the amount you need to borrow. It can also lower the lender’s risk and make your application more attractive.
2. Choose an affordable vehicle
Financing a less expensive vehicle may make approval easier because the loan amount is smaller.
3. Compare multiple lenders
Do not depend on only one dealership or bank. Credit unions, online lenders, and other financial institutions may have different approval requirements.
4. Consider a co-signer
A qualified co-signer with stronger credit may improve your chances of approval. However, the co-signer becomes responsible for the loan if you fail to make payments.
5. Review your credit report
Check for inaccurate information, outstanding balances, or accounts that may be affecting your score.
Can You Get a Car Loan With a Bad Credit Score?
Yes, some lenders provide car loans to people with poor credit scores, including borrowers below 580. These loans are often called bad-credit or subprime auto loans.
Although financing may be available, the terms can be expensive. You may receive a higher interest rate, need a larger down payment, or face stricter loan conditions.
Before accepting a bad-credit auto loan, carefully review:
- The annual percentage rate (APR)
- The total amount you will repay
- The loan duration
- Any additional fees
- Late payment penalties
- Whether the loan includes optional products or services
A low monthly payment does not always mean a good deal. A longer repayment period can make the total borrowing cost much higher.
If possible, spend some time improving your credit before purchasing a vehicle. Even a modest increase in your score could help you qualify for better financing.
Which Credit Score Do Car Lenders Use?
Car lenders may use different credit scoring models when evaluating an application. Many auto lenders use FICO-based scores, including industry-specific FICO Auto Scores.
A FICO Auto Score is designed for vehicle lending and may place different emphasis on information in your credit history compared with a standard FICO score.
Lenders may also review credit reports from one or more major credit bureaus:
- Experian
- Equifax
- TransUnion
Your scores can vary between bureaus because the information in each credit report may not be identical. The scoring model and version used can also affect the result.
This means the score you see through a free credit monitoring service may not be exactly the same score a dealership or lender uses.
How to Improve Your Credit Score Before Buying a Car
If you are planning to finance a vehicle in the next few months, improving your credit score can help you prepare for the application process.
Here are some practical steps to consider.
Pay every bill on time
Payment history is an important factor in many credit scoring models. Set reminders or automatic payments to avoid missing due dates.
Reduce credit card balances
High credit card utilization can negatively affect your score. Paying down balances may improve your credit profile, particularly when lower balances are reported to the credit bureaus.
Avoid unnecessary new credit applications
Opening several accounts in a short period can create multiple hard inquiries and may affect your score. Avoid applying for credit you do not need before seeking an auto loan.
Check your credit reports
Review your reports from Experian, Equifax, and TransUnion. If you find inaccurate information, dispute it with the relevant credit bureau.
Keep older accounts in good standing
The length of your credit history can contribute to your credit profile. Avoid closing older accounts without considering the possible effects.
Pay down existing debt
Reducing outstanding debt can improve your overall financial position and may help lenders view your application more favorably.
Credit improvement takes time. Accurate negative information generally cannot be removed simply by requesting its deletion, so focus on building consistent positive financial habits.
Does a Down Payment Help You Get Approved for a Car Loan?
Yes. A down payment can make a car loan application stronger, particularly if your credit score is not very high.
When you pay part of the vehicle’s price upfront, you reduce the amount you need to finance. This can lower your monthly payment and reduce the total interest you pay.
For example, if you purchase a $30,000 vehicle and make a $5,000 down payment, you would need to finance $25,000 before taxes, fees, and other charges.
A larger down payment may also reduce the risk of owing more than the vehicle is worth as it depreciates.
However, do not use all your available savings for a down payment. Keep enough money for insurance, registration, maintenance, fuel, and unexpected expenses.
Should You Get Preapproved Before Visiting a Car Dealership?
Getting preapproved for an auto loan can make the buying process easier. It allows you to understand your potential interest rate, loan amount, and monthly payment before negotiating with a dealership.
Preapproval can also help you compare financing options and avoid focusing only on the monthly payment.
Before accepting an offer, compare:
- The APR
- The loan term
- The total repayment amount
- Any origination or processing fees
- Early repayment conditions, if applicable
A dealership may offer financing through its network of lenders, but you are not required to accept the first offer. Comparing it with a bank or credit union offer can help you make a better decision.
Final Thoughts
A credit score of 670 or higher is generally a good starting point when buying a car in the United States, while scores above 740 may provide access to more competitive financing opportunities. However, you do not need perfect credit to qualify for an auto loan. Lenders also consider your income, debt, down payment, payment history, and the vehicle you want to purchase. Before applying, check your credit reports, compare loan offers, and choose a monthly payment that comfortably fits your budget. Preparing in advance can help you secure financing without paying more than necessary.
Frequently Asked Questions
1. Is 650 a good credit score to buy a car?
A 650 credit score is generally considered fair under FICO guidelines. You may qualify for an auto loan, but the interest rate could be higher than what borrowers with good or excellent credit receive.
2. Is 700 a good credit score for a car loan?
Yes. A 700 credit score is generally considered good and can help you qualify for competitive auto loan offers. Your final rate will still depend on your income, debt, vehicle, and lender.
3. Can I buy a car with a 500 credit score?
It may be possible to finance a car with a 500 credit score through lenders that specialize in poor-credit borrowers. However, you may face high interest rates and stricter requirements.
4. Does buying a car improve your credit score?
An auto loan can help build your credit history when you make payments on time. However, applying for a loan may result in a hard inquiry, and taking on additional debt can affect your credit profile.
5. How long should I wait to buy a car after improving my credit score?
There is no fixed waiting period. You can consider applying once your updated credit information has been reported and your financial situation is ready for a loan. Checking your credit reports before applying can help you choose the right time.